Most robo advisor content is comparison-shopping material, ranking providers by fee level and available account types without ever explaining what is actually happening inside the portfolio on an ongoing basis. Two of the most important mechanisms, automatic rebalancing and tax-loss harvesting, are frequently mentioned as selling points but rarely explained in terms of the actual mechanics involved. Understanding how these processes actually work helps clarify what you are paying an advisory fee for, beyond simply having your money allocated across a preset mix of index funds.
- Why Portfolios Drift From Their Target Allocation
- How the Rebalancing Actually Happens
- Using New Contributions to Rebalance Without Selling
- How Tax-Loss Harvesting Actually Works
- Why the Substitute Security Can’t Be Too Similar
- How Often Tax-Loss Harvesting Actually Happens
- What This Means for the Fee You’re Paying
- Bottom Line
- Frequently Asked Questions
- Sources
Core Robo Advisor Automation Features
| Feature | What It Actually Does | Why It Matters |
|---|---|---|
| Automatic rebalancing | Buys and sells holdings to maintain your target allocation | Prevents portfolio drift from changing your risk level over time |
| Threshold-based triggers | Rebalances when an asset class drifts beyond a set percentage | Avoids unnecessary trading from minor daily fluctuations |
| Tax-loss harvesting | Sells a losing position and buys a similar substitute | Captures a tax deduction while staying invested |
| Wash-sale avoidance | Avoids repurchasing a substantially identical security within 30 days | Ensures the harvested loss remains tax-deductible |
Why Portfolios Drift From Their Target Allocation
When you set up an account with a robo advisor, you are typically assigned a target allocation, for example 80 percent stocks and 20 percent bonds, based on your stated risk tolerance and time horizon. Because different asset classes grow at different rates over time, a portfolio that starts at exactly 80/20 will naturally drift away from that target as markets move, often ending up more heavily weighted toward whichever asset class has performed better recently. Left unaddressed, this drift can gradually shift a portfolio’s actual risk level well beyond what the investor originally intended, which is the core problem automatic rebalancing is designed to solve.
How the Rebalancing Actually Happens
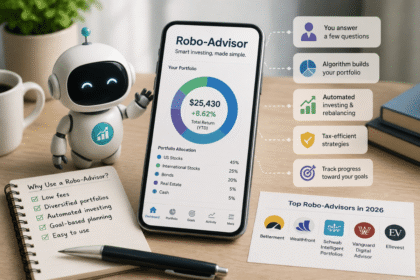
Most robo advisors use one of two triggering approaches for rebalancing, either checking allocations on a set schedule, such as quarterly, or continuously monitoring for drift and triggering a rebalance whenever any asset class moves beyond a specific threshold, often somewhere around 5 percentage points from its target. When a rebalance is triggered, the platform’s algorithm sells a portion of the overweighted asset class and uses the proceeds to buy more of the underweighted one, restoring the portfolio to its original target percentages. This happens automatically without the investor needing to place any trades themselves, which is part of the core value proposition of using an automated platform rather than manually managing individual rebalancing decisions.
Using New Contributions to Rebalance Without Selling
A more tax-efficient rebalancing technique many robo advisors use, particularly in taxable accounts, is directing new incoming contributions toward whichever asset class is currently underweighted, rather than immediately selling existing holdings to force the portfolio back into balance. This approach, sometimes called cash flow rebalancing, achieves the same end goal of restoring target allocations but avoids triggering a taxable sale in the process, since no existing positions need to be liquidated if ongoing contributions are large enough to correct the drift on their own.
How Tax-Loss Harvesting Actually Works
Tax-loss harvesting involves selling a security that has declined in value to realize a capital loss, which can offset capital gains elsewhere in your portfolio or, up to an annual limit, offset a portion of your ordinary income for tax purposes. The mechanical challenge is that simply selling a losing position and holding cash defeats the purpose of staying invested, so robo advisors immediately reinvest the proceeds into a similar, though not identical, security that maintains comparable market exposure. For example, sale proceeds from one broad US stock market ETF might be reinvested into a different, similarly structured ETF tracking a comparable but not identical index, preserving your overall market exposure while realizing the tax loss.
Why the Substitute Security Can’t Be Too Similar
The IRS wash-sale rule prohibits claiming a tax loss if you purchase a substantially identical security within 30 days before or after the sale, which is why robo advisors are careful to select a substitute fund that tracks a different, though economically similar, index rather than simply buying back the same fund. Getting this wrong would invalidate the tax benefit entirely, so robo advisor platforms typically maintain pre-approved pairs of similar funds specifically designed to avoid running afoul of the wash-sale rule while still preserving the portfolio’s intended market exposure during the substitution period.
How Often Tax-Loss Harvesting Actually Happens
Rather than checking for harvesting opportunities only once a year around tax season, most robo advisor platforms scan portfolios daily for tax-loss harvesting opportunities, since a stock market decline that creates a harvestable loss can happen, and reverse, within a matter of days. This daily monitoring is one of the genuine advantages of an automated system over manual tax-loss harvesting, since a human investor manually managing this process would need to check prices and execute trades far more frequently than is practical to capture the same opportunities consistently.
What This Means for the Fee You’re Paying
Understanding these mechanics helps clarify what a robo advisor’s typical advisory fee, often in the range of 0.25 percent annually, is actually paying for beyond basic portfolio allocation: ongoing, automated monitoring and execution of rebalancing and tax-loss harvesting that would otherwise require regular manual attention to replicate. For investors in a taxable account with a meaningful balance, the tax savings generated by consistent tax-loss harvesting alone can, in some years, offset a substantial portion of the advisory fee, though this benefit is less relevant for investors holding funds exclusively in tax-advantaged retirement accounts where there are no capital gains taxes to offset in the first place.
Bottom Line
Robo advisors provide more than a static, preset investment allocation; the automatic rebalancing and tax-loss harvesting running continuously behind the scenes are doing real, ongoing work to maintain your intended risk level and capture tax benefits that would be impractical for most individual investors to replicate manually with the same consistency. Understanding these mechanics, rather than treating the platform as a black box, makes it easier to evaluate whether the advisory fee you’re paying is delivering genuine value for your specific account type and balance.
Frequently Asked Questions
Does automatic rebalancing trigger a taxable event in my taxable account?
It can, if it involves selling existing holdings that have appreciated. Many robo advisors try to minimize this by using new contributions to rebalance where possible before resorting to selling appreciated positions.
Is tax-loss harvesting useful in a retirement account like an IRA?
No, generally not. Tax-loss harvesting is designed to offset capital gains taxes, which do not apply within tax-advantaged accounts like traditional or Roth IRAs, so this feature is primarily relevant for taxable brokerage accounts.
Can tax-loss harvesting accidentally violate the wash-sale rule?
Robo advisor platforms are specifically designed to select substitute securities that avoid the wash-sale rule, which prohibits buying a substantially identical security within 30 days of the sale. This is one of the more technically complex parts of the automation.
How often do robo advisors actually rebalance my portfolio?
This varies by platform, but many use either a set schedule, such as quarterly, or continuous monitoring that triggers a rebalance whenever an asset class drifts beyond a specific percentage threshold from its target.
This article is for general informational purposes only and is not financial or tax advice. Consult a qualified financial or tax professional regarding your specific situation.